

Drivers are often surprised to learn they may be required to carry SR-22 insurance even when they do not own a car. Courts and state motor vehicle departments focus on driver risk and financial responsibility rather than vehicle ownership. Understanding who needs non-owner sr22 coverage helps drivers meet legal obligations, avoid license delays, and move forward without unnecessary complications.
IIS Insurance Services works with drivers across many states who need clear, practical guidance after license suspensions, DUIs, or serious traffic violations.
What Non-Owner SR-22 Insurance Coverage Actually Is
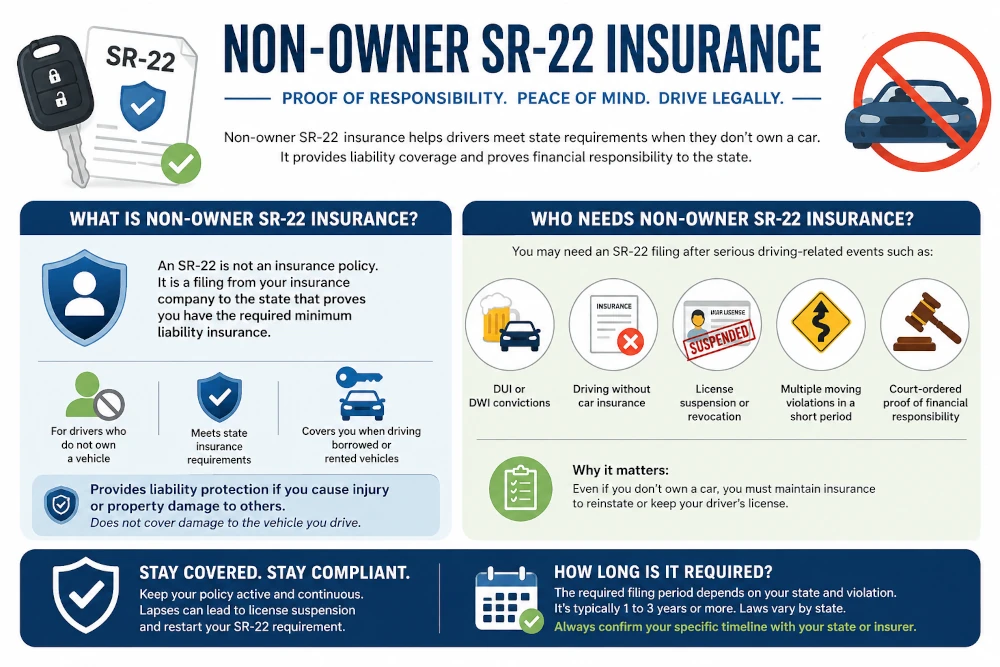
An SR-22 is not an auto insurance policy. It is an insurance filing submitted by an insurer to the state confirming that a driver carries the required minimum liability insurance.
A non-owner SR-22 non-owner policy is designed for drivers who:
- Do not own a vehicle
- Still need to meet state insurance requirements
- Plan to drive only borrowed or rented cars
The insurance coverage attached to the filing provides liability protection for injuries or property damage caused to others. It does not cover damage to the vehicle being driven, and it does not replace standard car insurance for owned vehicles.
States require this filing to ensure that higher-risk drivers maintain continuous insurance coverage before driving privileges are restored or retained.
Drivers Who Need Non-Owners Insurance After Serious Violations
Non-owners insurance with an SR-22 filing is typically required after serious driving-related events. Courts and state agencies impose the requirement when a driver’s record shows elevated risk.
Common situations include:
- DUI or DWI convictions
- Driving without car insurance
- License suspension or revocation
- Multiple moving violations in a short period
- Court-ordered proof of financial responsibility
Even if a driver no longer owns a vehicle, they must still maintain insurance coverage if they want to reinstate or keep a valid driver license. Many drivers in this position purchase non-owner insurance to meet legal requirements without insuring a vehicle they do not own.
IIS Insurance Services helps drivers confirm whether their situation requires non-owners insurance and explains the steps needed to comply.
Why Not Owning a Vehicle Does Not Remove the Insurance Requirement
A common misconception is that selling a car or choosing not to drive eliminates the need for SR-22 insurance coverage. In reality, states base the requirement on driving history, not vehicle ownership.
If a driver wants to maintain or restore driving privileges, proof of liability insurance is still required. A non-owner policy allows drivers to meet that requirement without carrying standard auto insurance on a vehicle they do not own.
From the state’s perspective, this approach ensures public protection by requiring any licensed driver to carry insurance before legally driving again.
How a Non-Owner Policy Works in Real-World Driving
A non-owner policy follows the driver, not a specific vehicle. Coverage applies when the insured driver operates a vehicle that they do not own.
This typically includes:
- Rental cars
- Borrowed vehicles from friends or family
- Occasional driving situations
It does not apply to:
- Vehicles owned by the driver
- Vehicles are regularly available to the driver
- Household vehicles
Because coverage is limited to liability insurance, non-owner policies are often more affordable than standard auto insurance policies that insure owned vehicles.
State Rules That Affect Non-Owner Insurance Coverage
Each state sets its own rules regarding SR-22 insurance filings. These rules determine how long the filing is required, when it begins, and what happens if coverage lapses.
State-specific differences may include:
- Length of the required filing period
- Minimum liability insurance limits
- Penalties for missed payments
- License reinstatement procedures
Some states require one year of continuous coverage, while others require three years or longer. The requirement usually begins when the insurance filing is accepted by the state, not when the violation occurred.
Drivers who move to another state must still satisfy the original state’s requirement.
IIS Insurance Services helps drivers understand state-specific timelines and compliance rules.
License Suspension and Reinstatement Situations
License suspension is one of the most common reasons drivers need non-owners insurance with an SR-22 filing. Suspensions often follow DUIs, uninsured driving, or repeated violations.
In these cases, states commonly require:
- Proof of insurance coverage
- Payment of reinstatement fees
- Completion of court-ordered programs
A non-owner policy allows drivers to meet insurance requirements while working toward reinstatement, even if they do not own a vehicle. Failing to maintain coverage can delay reinstatement or result in additional penalties.
High-Risk Driver Classification and Insurance Availability
Drivers required to file an SR-22 are usually classified as high-risk. This classification affects pricing and availability across auto insurance carriers.
Factors that influence high-risk status include:
- Severity of violations
- Number of prior offenses
- Time since the last incident
Non-owners insurance provides a practical solution for high-risk drivers who need legal insurance protection without owning a vehicle.
IIS Insurance Services works with insurers experienced in high-risk cases to help drivers secure compliant coverage.
What Happens If Insurance Coverage Lapses
Coverage lapses are one of the most costly mistakes drivers make during an SR-22 requirement. Insurers are required to notify the state if a policy cancels or lapses.
A lapse may result in:
- Immediate license suspension
- Restart of the SR-22 requirement period
- Additional fines or penalties
Even a brief lapse can reset the entire timeline. Drivers should plan renewals carefully and keep payment information current to maintain uninterrupted protection.
How Long Non-Owner Insurance Is Required
The length of time a driver must carry non-owner SR-22 insurance depends on state law and the underlying violation. Three years is common, but not universal.
Important reminders include:
- The policy term and SR-22 filing period are separate
- Policies may renew multiple times during the requirement
- Continuous insurance coverage is mandatory
Drivers should confirm their specific timeline with the state or their insurance provider before making changes.
Ending a Non-Owner SR-22 Requirement the Right Way
SR-22 requirements do not end automatically. Drivers must verify that the obligation has been fully satisfied before canceling coverage.
Recommended steps include:
- Confirming the required time period has passed
- Verifying clearance with the state
- Waiting for confirmation before canceling the policy
Canceling too early can restart the requirement and lead to new penalties.
IIS Insurance Services helps drivers track timelines and confirm when it is safe to remove the insurance filing.
Why a Non-Owner Policy Is Often the Best Option
For drivers without vehicles, a non-owner policy offers a balanced approach to compliance and cost. It allows drivers to:
- Meet legal insurance requirements
- Avoid paying for unnecessary auto insurance
- Maintain or restore driving privileges
Courts and state agencies widely accept this form of coverage when it is maintained correctly and without lapses.
Getting Help With Non-Owner SR-22 Coverage
Navigating SR-22 requirements can feel overwhelming, especially when deadlines and legal consequences are involved. Reliable guidance helps drivers avoid missteps that extend the process.
IIS Insurance Services supports drivers by explaining who needs non-owner SR-22 coverage, securing appropriate policies, and helping maintain continuous compliance. Whether you are just starting the process or nearing completion, having knowledgeable support makes the path forward clearer.
Drivers who need help determining whether non-owner SR-22 coverage applies to their situation can contact IIS Insurance Services for clear answers and practical support.