

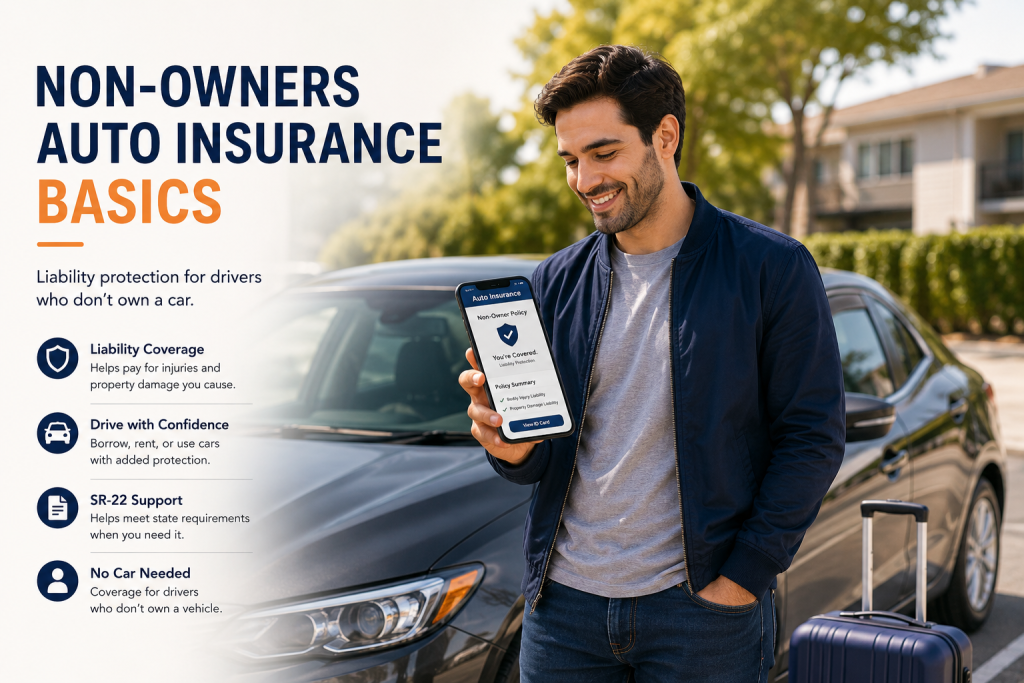
If you drive but don’t own a car, figuring out insurance can feel confusing. You may borrow a friend’s car, rent one for a weekend, use a car-sharing service, or need proof of insurance after a license issue. In those situations, standard car insurance may not fit because there is no personal vehicle to insure.
That’s where non owners auto insurance basics can help. A non-owner policy is a type of auto insurance built for drivers who don't own a vehicle but still need liability protection in certain driving situations. It can be useful for occasional drivers, people with SR-22 filing needs, and drivers who want to avoid a gap in insurance coverage.
Still, non-owner car insurance has limits. It usually does not cover damage to the car you drive. It may not apply if you use the same vehicle often. It also may not be the right choice if you live with the car owner or drive for work.
What a Non-Owner Policy Means
A non-owner policy is automobile insurance for a driver who does not own a car. Instead of listing a specific vehicle, the policy is connected to the driver. It may provide liability coverage when that driver uses a vehicle they don’t own, as long as the trip fits the policy terms.
This type of insurance is usually meant for occasional driving. For example, it may help if you borrow a car from a friend once in a while, rent a car for short trips, or need proof of insurance without vehicle ownership.
Non-owners insurance is different from owner car insurance. Owner car insurance is tied to a specific car, truck, or SUV. It can include coverages for that vehicle, such as collision or comprehensive, if those options are selected. A non-owner policy usually focuses on liability and does not insure the car itself.
For California drivers, this distinction matters. The state requires financial responsibility for vehicles operated or parked on California roads. Many drivers meet that requirement through car insurance. If you don't own a vehicle, a non-owner option may help in some situations, but it must match your driving habits, license status, and any filing needs.
What Liability Coverage Can Help With
The main purpose of non-owner car insurance is liability protection. Liability coverage can help pay for injuries or property damage you cause to other people in a covered accident.
For example, say you borrow a friend’s car to run an errand and cause an accident. The owner’s insurance policy may be reviewed first, depending on the policy and whether you had permission to drive. If the claim qualifies and extra liability protection is needed, your non-owner policy may be reviewed as well.
A non-owner policy may help with costs such as:
- Injury expenses for another driver, passenger, pedestrian, or cyclist
- Damage to another person’s car
- Damage to someone’s fence, garage, storefront, or other property
- Certain legal defense costs, depending on the insurance policy
- SR-22 filing support, if offered and required for your situation
The policy limits matter. If your coverage limits are low and the accident costs are high, you may still be responsible for costs above the policy limit. Higher limits may offer stronger protection, but your quote can change based on your driving record, location, license status, prior claims, and carrier rules.
A non-owner policy may also support continuous insurance coverage. Some drivers use it after selling a car, before buying another one, or while they only drive rented or borrowed vehicles. A gap in car insurance can affect future rates, so staying insured may help some drivers keep a cleaner insurance history.
Non-Owner Car Insurance Compared With Standard Car Insurance
The easiest way to understand non-owner insurance is to compare it with standard car insurance. One is built around the driver. The other is built around a vehicle.
| Question | Non-owner car insurance | Standard car insurance |
|---|---|---|
| Who is it for? | Drivers who do not own a vehicle | Drivers who own, lease, finance, or regularly use a car |
| Is a car listed? | Usually no | Yes |
| Does it usually include liability coverage? | Yes, if the policy applies | Yes, if selected and required by law |
| Does it usually cover damage to the car being driven? | Usually no | It may, with collision or comprehensive coverage |
| Can it help with SR-22 filing? | May be available for drivers without a car | May be available for drivers with a car |
| Does it fit daily use of the same vehicle? | Usually no | Usually yes |
| Can it cover business driving? | Usually no | Personal policies may still exclude business use |
| Is it used for rental cars? | May help with liability, depending on policy terms | May help, depending on the policy and rental agreement |
This comparison shows why the right choice depends on real use. If you own a car, standard auto insurance is usually the place to start. If you do not own a vehicle and only drive occasionally, a non-owner option may be worth asking about.
Cost is another difference. Non-owner policies often cost less than standard car insurance because they usually do not cover a specific vehicle or include physical damage protection. That lower cost can be helpful, but it also reflects narrower coverage.
Where Non-Owner Coverage Has Limits
A non-owner policy can be useful, but it is not a full replacement for standard car insurance. The biggest limit is vehicle damage. If you crash a borrowed or rented car, non-owner insurance usually does not pay to repair that car.
That means the owner’s insurance policy, rental company coverage, or another policy may need to respond if the vehicle is damaged. If no physical damage coverage applies, the cost may become an out-of-pocket issue.
Non-owner insurance may also fall short when the driver has regular access to a vehicle. If you use your roommate’s car every day, drive a partner’s car to work, or keep a borrowed car at your home, the insurance company may not treat that as occasional driving. You may need to be listed on the owner’s policy or use another coverage setup.
It may not fit if:
- You own a car
- You drive the same car every day
- You live with the vehicle owner and use their car often
- You keep a borrowed vehicle at your home
- You need collision or comprehensive coverage
- You drive for delivery, rideshare, courier work, or another business purpose
- You need coverage for tools, cargo, or personal items inside the car
- Your SR-22 requirement calls for a different filing type
Business use is a common issue. A personal non-owner policy usually is not designed for paid driving. If you use any vehicle for delivery, rideshare, trucking, client visits, or business errands, you may need commercial auto coverage or another business insurance option.
How to Know If Non-Owner Insurance Is Worth It
Non-owner insurance may be worth it if you drive often enough to need protection but do not own a vehicle. It can also help if you need to file an SR-22 and do not have a car registered in your name.
A good fit may look like this. You borrow a friend’s car once or twice a month. You rent cars when traveling. You recently sold your car and plan to buy another one later in the year. You need to keep car insurance active while you don’t own a vehicle. You need Non-Owner SR-22 insurance after a DUI, lapse, or license issue, and you qualify through a carrier.
It may not be worth it if you almost never drive, already have a standard auto policy, or regularly use the same household vehicle. In those cases, another option may offer a better match.
Before requesting a quote, gather a few details so the agent can give better guidance:
- Whether you own any vehicle
- How often you drive
- Whose car you usually drive
- Whether you live with the car owner
- Whether you rent cars during the year
- Whether you need SR-22 filing
- Whether you have a valid license
- Whether you use any vehicle for work
- Your recent driving and insurance history
Be honest about how you use a car. Insurance companies base coverage decisions on risk, access, and policy terms. A policy that looks affordable may not help if it does not match the way you actually drive.
Talk With IIS Insurance About Non-Owner Auto Options
Non-owner auto insurance can be helpful, but it needs to fit your real situation. If you borrow cars, rent vehicles, need SR-22 filing, or want to avoid a gap in coverage, IIS Insurance Services can help you compare your options.
Our California-based team works with drivers in many situations, including DUI history, suspended license concerns, high-risk status, no U.S. license, no vehicle ownership, and past insurance lapses. We’ll explain what a non-owner policy may cover, what it may leave out, and when standard car insurance or commercial auto coverage may be a better fit.
You don’t have to sort through it alone. Call IIS Insurance Services or request a quote online to speak with a licensed agent. We’ll help you understand your options, review available policies, and look for coverage that fits your driving needs, budget, and California requirements.
Fast help, friendly support, and straight answers can make non-owner insurance much easier to understand.