

Limo insurance in California is commercial auto coverage written for chauffeured transportation and filed with the CPUC under your TCP permit, and for a limo business the details change with every vehicle, chauffeur, and client you add. IIS Insurance Services is appointed with several general agencies that can write livery coverage, and our Uber Black and limo insurance in California page breaks down the coverage parts and the CPUC liability limits by seating capacity. Here we focus on running a limo company day to day: vehicles, chauffeurs, client certificates, busy seasons, and growth.
The limo owners we work with usually start with one stretch or SUV and add vehicles over time. Each step up changes the policy, and the owners who plan for it ahead of time avoid gaps and surprise bills.
Does your vehicle change your limo insurance?
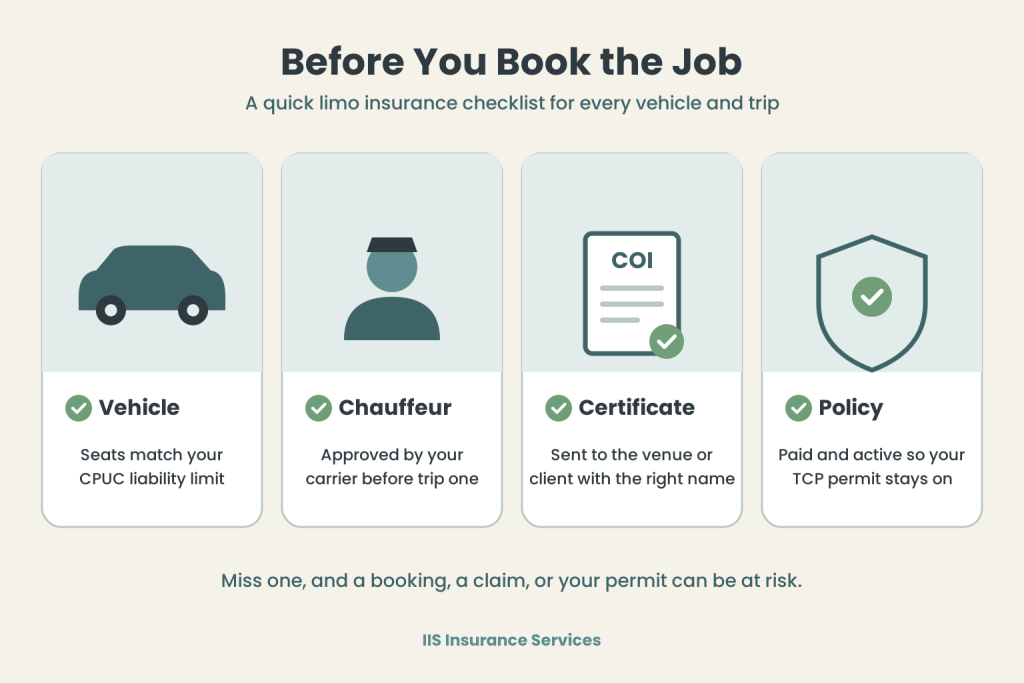
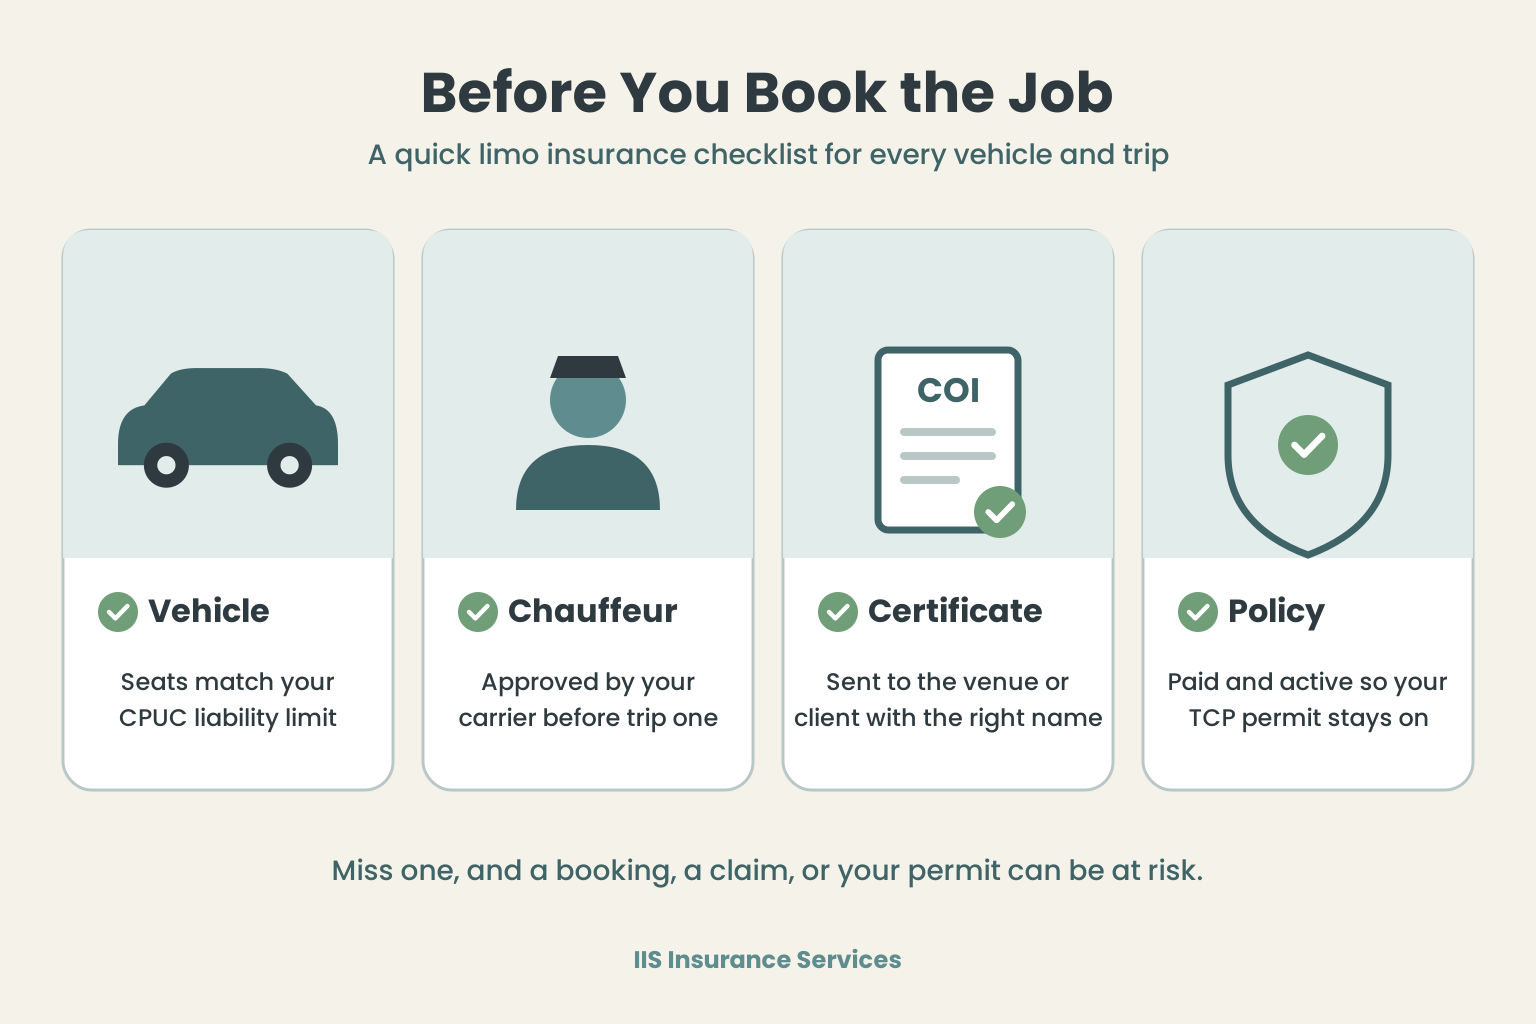
More than anything else. Seating capacity, including the driver, decides which CPUC liability tier you fall into: $750,000 for 8 or fewer people, $1.5 million for 9 to 15, and $5 million for 16 or more. Moving from a sedan or SUV to a 14-passenger Sprinter puts you in a higher tier, and your premium follows.
The type of vehicle matters too. Some livery markets are more cautious with stretch conversions, older vehicles, or very high-value vehicles, so it helps to talk to your agent before you buy, not after. A quick check on how a vehicle will rate can save you from buying something that costs far more to insure than you planned.
Hiring chauffeurs: what your insurer needs
Every chauffeur who drives for your limo company has to be listed on the policy and approved by the carrier before their first trip. The carrier will review each driver’s motor vehicle record and experience with chauffeured transportation.
- Send new driver information to your agent before they start, not after. Do not let your drivers drive before they’re added to your policy.
- Expect the carrier to decline drivers with recent major violations.
- One driver with a poor record can raise the price for the whole fleet.
- If chauffeurs are employees, plan for workers’ compensation. The CPUC asks about it during the TCP permit process.
Certificates for venues, hotels, and corporate clients
A lot of limo work comes with paperwork. Wedding venues, hotels, event planners, schools, and corporate accounts often ask for a certificate of insurance before you can pick up on their property, and many want to be listed as additional insured.
Ask for those requests early and send them to your agent with the client’s exact name and address. A certificate with the wrong name can hold up a booking. Airports have their own rules as well, so check each airport’s permit requirements before you book pickups there.
Prom season, weddings, and busy months
Limo work is seasonal. Some owners ask whether they can pause coverage in slow months. With a TCP permit, that usually isn’t a good idea: if the policy cancels, the carrier notifies the CPUC and your permit can be suspended. Getting it reinstated can take longer than the slow season itself.
A better approach is to talk to your agent about payment plans that fit your cash flow, and to keep your vehicle count accurate. If you sell a vehicle in the off-season, remove it from the policy. If you add one for prom or wedding season, add it before the first booking.
Growing from one limo to a small fleet
Two or three vehicles are usually written on one commercial auto policy with each vehicle and chauffeur listed. As you grow:
- Your liability limits and CPUC filing have to match your largest vehicle.
- Your claims history follows the business, so one accident can affect renewals for every vehicle.
- Driver hiring standards start to matter as much as the vehicles you buy.
- If you add Uber Black work, our post on how to get Uber Black insurance covers the extra steps with Uber, and our post on Uber Black car requirements in California covers which cars qualify.
What to do after an accident with passengers on board
An accident with clients in the vehicle is the situation every limo owner hopes to avoid, and how you handle the first hour matters for the claim.
- Check on everyone first. Call 911 if anyone is hurt, and make sure passengers are safe before anything else.
- Document the scene. Photos of the vehicles, the location, and any injuries, plus names and contact details for passengers and witnesses.
- Don’t discuss fault. Stick to the facts with the other driver and the police.
- Report it to your carrier quickly. Livery policies expect prompt notice, especially when passengers may have injury claims.
- Tell your agent. We can help you start the claim and answer questions about how it may affect your renewal, but the entire claim process is handled by the insurance company’s claims department.
Records that help at renewal time
Underwriters look at more than your claims history when your limousine insurance renews. Keeping a few things organized can help:
- Maintenance and inspection records for each vehicle
- A file for each chauffeur with their license, driving record, and hire date
- A written policy on phone use and passenger safety
- Records of any incidents, even ones that never became claims
A limo company that can show it runs a careful operation is easier to place, and that usually shows up in the options and pricing available to you.
What does limo insurance cost in California?
For a single sedan or SUV, the 2026 quotes we’re seeing run roughly $1,000 to $1,500 a month. Stretch limos, Sprinters, and party buses in the higher CPUC tiers cost more, and so does a fleet with newer chauffeurs. If a limo insurance quote comes in at a few hundred dollars a month, ask whether it’s really commercial livery coverage that can be filed with the CPUC.
Questions to ask your limousine insurance agent
- Does my liability limit match the seating capacity of every vehicle?
- How fast can you issue a certificate for a venue or corporate client?
- What’s the process for adding a chauffeur?
- Will the carrier insure a stretch conversion or an older vehicle?
- Are there payment plan options for the slow season?
Frequently asked questions
How is limo insurance different for a company with several drivers?
The policy type is the same livery coverage, but a limo company usually has more chauffeurs to approve, more client certificates to issue, and larger vehicles in higher CPUC tiers. Each of those affects the price.
Can I add a vehicle just for prom season?
Yes, but add it before its first trip, and make sure your liability limits fit its seating capacity.
Do venues really require certificates?
Many do, especially hotels, wedding venues, and corporate clients. Ask early so your agent can issue the certificate with the right name.
Does a party bus need different coverage than a sedan?
It’s still livery coverage, but a party bus usually seats 16 or more people, which puts it in the $5 million CPUC tier. Fewer markets write party buses, so expect more questions from the underwriter.
Get a limo insurance quote
If you own a limo or chauffeured transportation business in California, call IIS Insurance Services at (877) 210-9514. We’ll set your policy up around your vehicles, chauffeurs, and clients, and the insurance company keeps your CPUC filing on record while the policy is active.
For the official requirements, see the CPUC’s General Order 115-G and the California Public Utilities Commission website.
Reviewed by George Karapetyan, IIS Insurance Services. CA license #0E94849, agency license #0G56765. Last reviewed October 2026.