

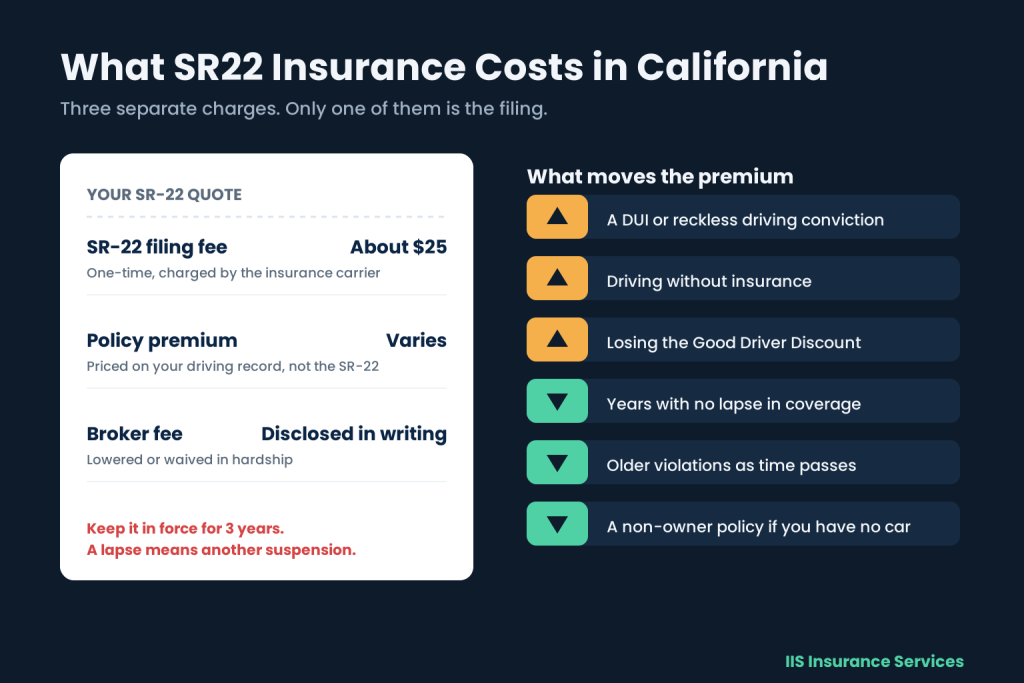
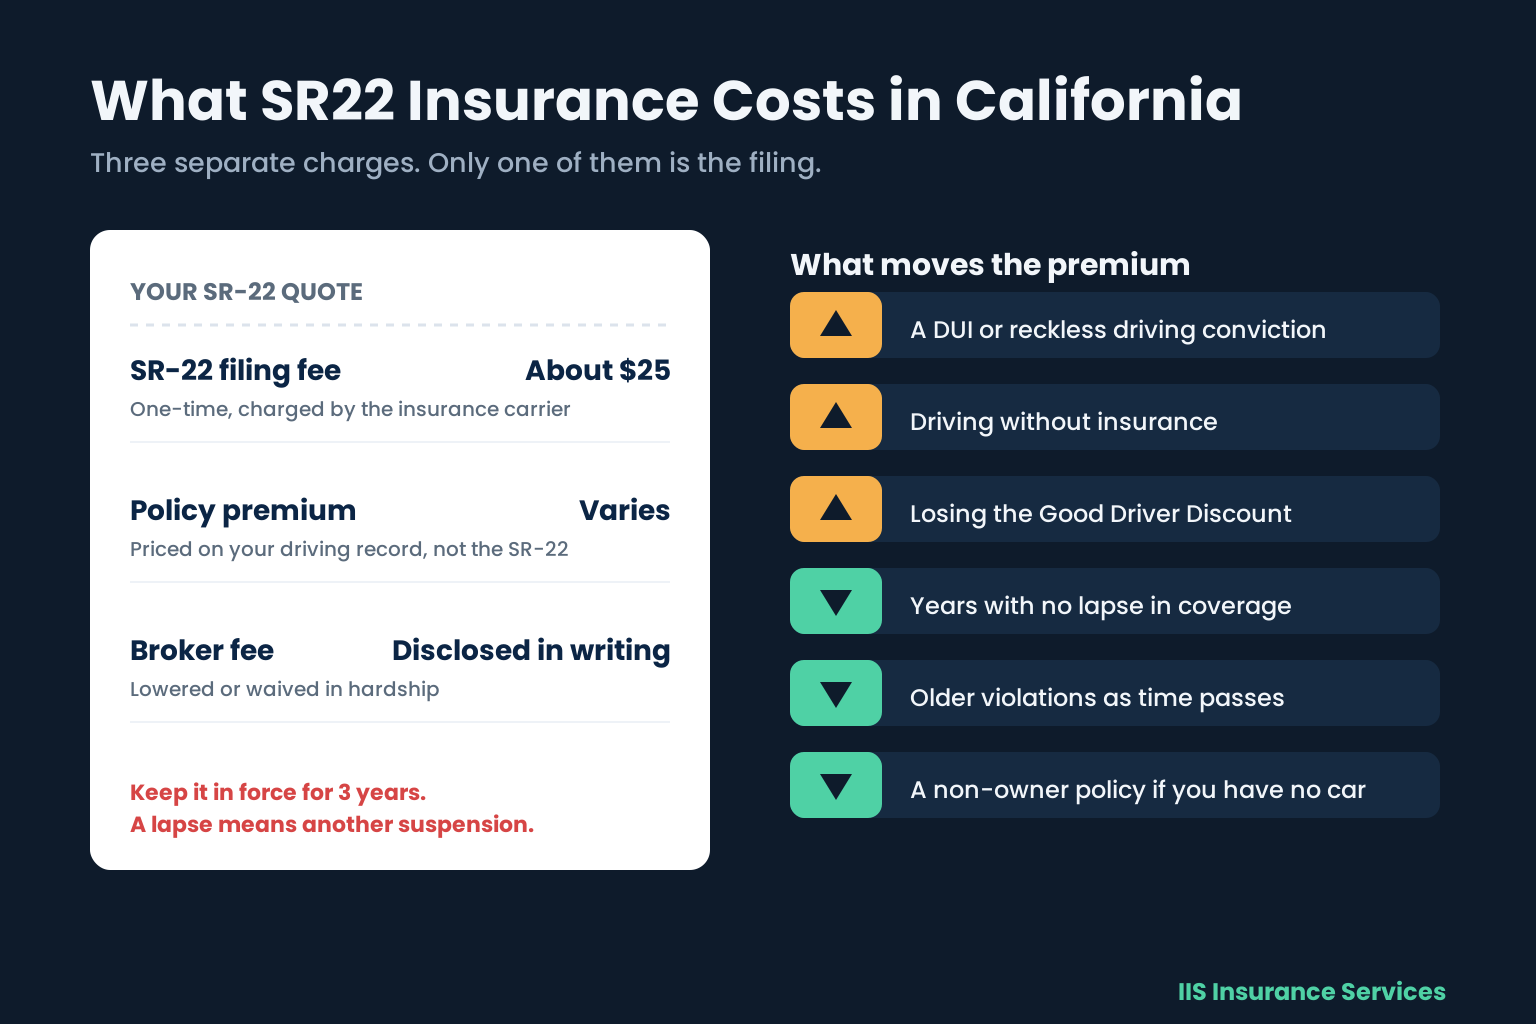
Wondering how much SR22 insurance costs in California? The SR-22 filing itself averages about $25. It is the violation behind the requirement, not the form, that raises your car insurance premium. Your rate depends on the offense, your driving record, the coverage you choose, where you live in the state, and the insurance company. Our page on SR-22 insurance in California covers the filing in general. This post breaks down the cost: the three charges you’ll see, what moves the premium up or down, and how to keep it from going up again.
California SR-22 Cost: The Filing Fee and Your Insurance Premium
At IIS Insurance Services, the first question we hear is how much SR22 insurance costs in California. The answer has three parts, and it helps to look at them separately when you compare quotes:
- The SR-22 filing fee. The insurance carrier charges this to file the certificate with the DMV. It averages about $25 and is usually a one-time charge.
- The policy premium. This is the car insurance itself, and it is the larger cost by far. Most drivers pay it monthly, and the first year after a violation is usually the most expensive. It is priced on your driving record, not on the SR-22.
- The broker fee. Most SR-22 agencies charge one. It has to be disclosed to you in writing before you buy. IIS Insurance Services charges broker fees too, but we never turn anyone away, and we lower or waive the fee for people going through a tough time.
Average SR-22 Insurance Cost in California: Why There Is No Single Number
There is no dependable statewide average for SR-22 car insurance in California, and any site that quotes one is guessing. Two drivers with the same car in the same ZIP code can pay very different premiums because one has a DUI and the other has a lapse in coverage. Premiums depend on your driving record, your years of driving experience, your ZIP code, your vehicle, your prior insurance, the liability limits you choose, and whether you need an owner or non-owner policy.
A low advertised rate often reflects minimum state liability coverage, which may not be enough for your situation. We compare auto insurance quotes from the insurance companies that accept SR-22 drivers and explain what each quote includes before you choose.
| Cost | What it covers | What sets the amount |
|---|---|---|
| SR-22 filing fee | The insurance carrier filing the certificate with the DMV | Set by the insurance carrier; about $25 on average |
| Policy premium | The car insurance policy behind the SR-22 | Your driving record, experience, ZIP code, vehicle, prior coverage, and limits |
| Broker fee | The agency’s charge for placing the policy | Set by the agency and disclosed in writing; we lower or waive it for drivers in hardship |
| Keeping it in force | Three years of continuous coverage | A lapse means the insurance company tells the DMV and you can be suspended again |
When California Drivers Need an SR-22 and What Coverage Must Include
An SR-22 is not a type of auto insurance policy. It is a certificate your insurance carrier files electronically with the California DMV to confirm you carry the required liability coverage. The state DMV or the court decides when you need one, not the insurance company. California drivers commonly need an SR-22 after a DUI, a reckless driving conviction, an accident without insurance, too many points, or a court order.
To get your license back, the policy behind the SR-22 has to meet the state minimum liability limits: $30,000 for injury or death to one person, $60,000 for injury or death to more than one person in one accident, and $15,000 for property damage. Liability pays for harm you cause to other people. It does not repair your own car. You can choose higher limits, and we often suggest them for drivers with a financed car. Our post on SR22 insurance coverage explains what each coverage does.
Once your license is reinstated, the SR-22 stays on file for three years. If the policy cancels, lapses, or you miss a payment, the insurance company has to notify the DMV, and your license can be suspended again. The goal isn’t the lowest premium this month. It’s coverage you can keep in force for the full three years.
- The DMV or the court decides whether you need an SR-22 filing.
- Common triggers: DUI, driving without insurance, too many points, and court orders.
- The policy must carry at least the state minimum of 30/60/15 liability limits.
- Keep the coverage active. A lapse can mean another suspension.
- The SR-22 stays on file for three years.
What Can Raise or Lower SR-22 Car Insurance Quotes
Your driving record carries the most weight. A DUI, a reckless driving conviction, an at-fault accident, a lapse in car insurance, or several violations in a short time all lead to higher premiums, because the insurance company sees a greater chance of another claim or another suspension. How old each incident is matters too. As violations move further into the past and you keep continuous car insurance, your rates can improve at each renewal.
Driving Record, Coverage and Liability Limits
California law also decides what an insurance company can and can’t use to price you. Under Proposition 103, the main rating factors are your driving record, how many miles you drive, and your years of driving experience. Credit scores are not allowed in auto insurance rates in this state. The Good Driver Discount is one of the largest discounts available, and you lose it with a DUI conviction in the past 10 years or more than one point on your record. That lost discount is a big part of why an SR-22 driver’s premium goes up.
Coverage choices shape the quote as well. Minimum liability gives the lowest upfront price, but it can leave you exposed after a serious crash. Adding collision, comprehensive, uninsured motorist coverage, or higher limits raises the policy cost. Those choices are often worth it, depending on your vehicle and what you have to protect. A paid-off older car lets you keep the premium low by skipping physical damage coverage. A financed vehicle requires it.
Here is what moves the price the most:
- A recent DUI, serious conviction, at-fault accident, or several violations raises the premium.
- Continuous coverage with no lapses, and older incidents, bring rates down over time.
- Higher liability limits and physical damage coverage cost more.
- Your ZIP code, vehicle, annual mileage, years of experience, and prior insurance all count.
- A non-owner SR-22 policy is usually the least expensive option if you don’t own a car.
Low Rates vs. Car Insurance Quotes That Leave Gaps
It pays to compare car insurance quotes with the same limits and deductibles on each one. Not every insurance company accepts every record, and the one that is cheapest for a lapse in coverage is often not the cheapest after a DUI. We compare the companies that accept your situation and explain the filing fee, the broker fee, and the policy terms before you decide.
File an SR-22 With the California DMV and Avoid a Coverage Lapse
For a driver working to get a suspended license reinstated after a DUI, an uninsured accident, or another violation, the SR-22 is usually the step that lets the DMV move forward once everything else on the notice is done. We start by confirming what the DMV requires, then get quotes from the insurance companies willing to write the policy for your record. Once the policy starts, the insurance carrier files the SR-22 with the DMV, usually the same day. Our post on the cheapest SR22 insurance with same-day filing explains how fast the filing can happen.
Filing With the State and Switching Insurance Companies
The most important thing after the filing is keeping the policy active. Pay on time, respond to renewal notices, and contact us before you change cars, move, or switch insurance companies. If you switch, the new company has to file its SR-22 before the old policy ends, or the DMV sees a lapse. We help drivers compare options without putting the continuous coverage their SR-22 depends on at risk.
Frequently Asked Questions
How much is an SR-22 in California per month?
The SR-22 filing fee is about $25, usually one time. The monthly cost is the car insurance premium, and that depends on your record, your car, your ZIP code, and your coverage. Insurance quotes for the same driver can differ a lot from one company to the next. There is no single monthly number that fits every driver.
What is the cheapest SR-22 car insurance in the state?
A non-owner SR-22 policy is usually the least expensive, because it only carries liability coverage. If you own a car, the cheapest policy is the one from the insurance company that prices your specific violation the best, which is why we compare several.
How long does an SR-22 stay on your insurance in California?
Three years from reinstatement. Confirm the end date with the DMV before you cancel or change your policy.
What are the requirements to get an SR-22 in California?
A liability policy with at least 30/60/15 limits, from an insurance carrier that files SR-22s with the California DMV, kept in force for three years with no lapses.
Does an SR-22 raise my insurance rates?
The filing itself doesn’t raise your auto insurance rates. The violation that caused it does, mostly because you lose the Good Driver Discount and some companies won’t write the policy at all.
Get an SR-22 Quote Today
Call IIS Insurance Services at (877) 210-9514. We have been placing SR-22 filings in California since 2009. We compare the insurance companies in the state that accept your record, explain every cost in writing, and have the SR-22 filed with the DMV, usually the same day. We can help you in seven languages. For the official rules on your suspension, check with the California DMV.
Reviewed by George Karapetyan, IIS Insurance Services. CA license #0E94849, agency license #0G56765. Last reviewed October 2026.