

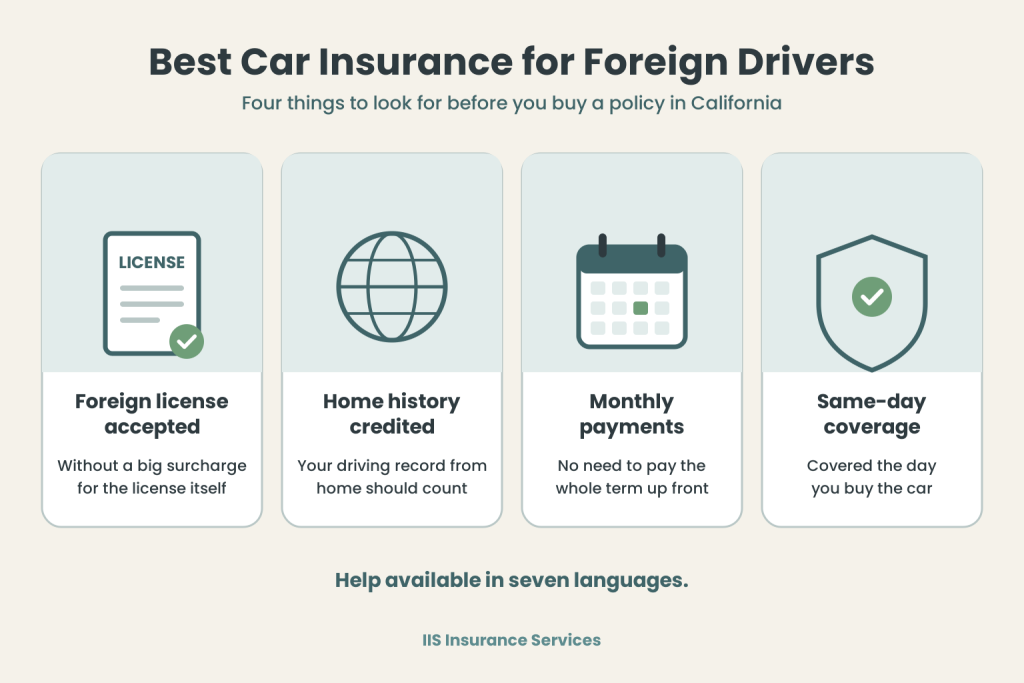
The best car insurance for foreign drivers in California is a policy from a carrier that accepts your foreign license without a big surcharge, gives you credit for your driving history back home, lets you pay monthly, and can start coverage the same day. IIS Insurance Services works with insurance companies that do all of that, and our page on auto insurance with a foreign or international license in California explains the license rules. Here we cover the car insurance buying decision itself: what to compare, which shortcuts to avoid, and how to tell a good quote from one that only looks cheap.
It’s common for foreign drivers to hear “we can’t insure you” from the first companies they call. That usually says more about the company than about the driver. Some insurance providers simply don’t write foreign licenses, and others write them but price them as if the driver has never been behind the wheel.
The short version
- “Best” for a foreign driver means four things: the license is accepted with no surcharge (or at least no big one), home-country history counts, monthly payments are available, and coverage can start the same day.
- Carriers price you on the usual things: the car, your ZIP code, your age, and your record. The license alone shouldn’t double your quote.
- Be honest on the application about your license and who drives the car. A cheaper quote built on wrong information can cost you a claim.
- Compare limits and deductibles, not just the monthly number.
What makes the best car insurance for foreign drivers?
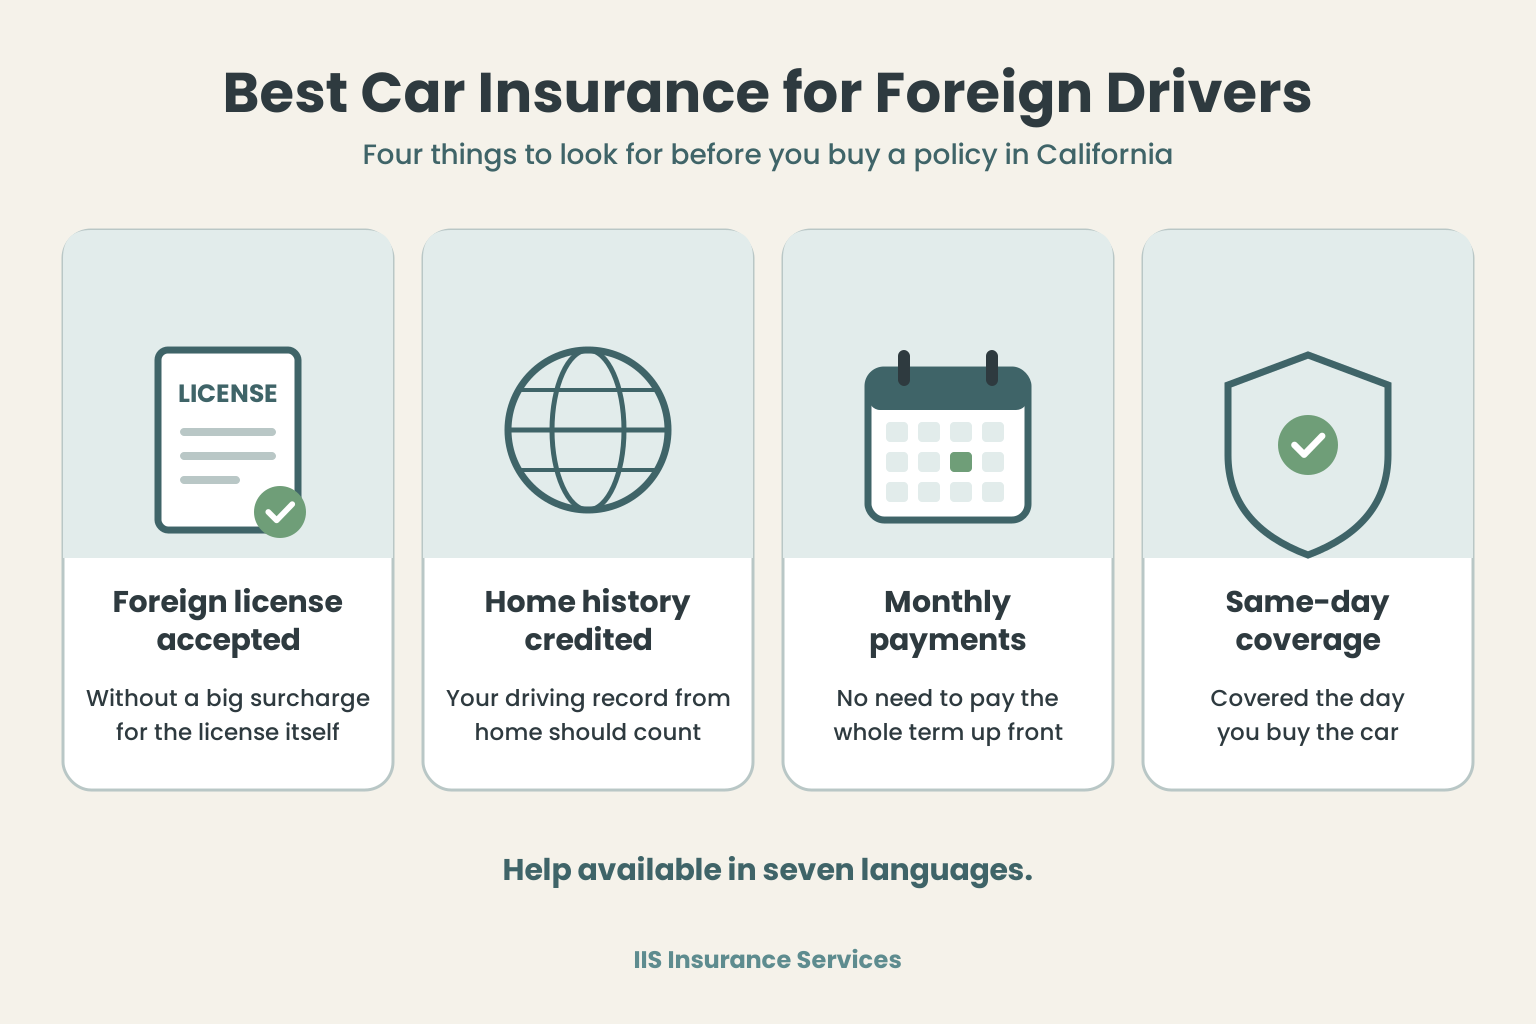
Most rankings of insurance companies are written for drivers with a long U.S. record. They don’t help much when your license was issued in another country. For foreign drivers, these are the things that decide whether a carrier is a good fit:
| What to look for | Why it matters to a foreign driver |
|---|---|
| Accepts foreign and international licenses | Some carriers won’t quote you at all until you have a California license. You need one that will. |
| No surcharge, or no significant surcharge, for the license itself | Your price should come from the same underwriting factors as anyone else, not from where your license was issued. |
| Credits home-country driving history | Ten years of driving at home should count for something. The carriers we use most will count it, as long as you can document it. |
| Monthly payments | New arrivals are often paying deposits, rent, and a car at once. Paying the whole term up front isn’t realistic for many people. |
| Same-day coverage | When you buy a car, the dealer or seller won’t wait a week. Coverage can start the day you call, once the paperwork and first payment are in. |
| Help in your language | Insurance terms are hard enough in your first language. IIS Insurance Services can help you in seven languages. |
How insurance companies price a foreign license
There’s no special formula for foreign drivers. The carrier looks at the same things it looks at for everyone: the vehicle, the ZIP code where it’s kept, your age, your driving record, any claims, how much you drive, and the coverage options you pick. Where foreign drivers lose money is on the driving record. If the carrier can’t see your history, it may rate you like a new driver.
That’s why the documents you bring matter more than which company’s name is on the policy. If possible, request a copy of your record from the agency that issued your license, plus a no-claims letter from your last insurer that lists your coverage dates. An English translation makes the underwriter’s job easier. With those in hand, the carrier sees real experience instead of a blank page.
What doesn’t usually change your price much
- Having an International Driving Permit (IDP). It’s a translation that travels with your license. It helps the carrier read your license, but it isn’t a license or a driving record on its own.
- Your country of origin. Carriers rate the driver and the car. They don’t add a surcharge because of where you were born.
Shortcuts that make the price look better and cost you later
These come up a lot, and every one of them can turn into a denied or reduced claim:
- Listing a friend or relative with a U.S. license as the main driver. If you’re the one driving the car every day, you have to be on the policy as the driver. Putting someone else’s name there to get a lower insurance quote is misrepresentation, and the carrier can refuse to pay when they find out after an accident.
- Leaving a driver off the policy. Anyone in your household who drives the car regularly should be listed.
- Relying on insurance from your home country. A policy bought abroad usually doesn’t meet California requirements for a car you live with and drive here. Check with us before you count on it.
- Choosing only by the monthly number. A low payment can hide a $2,000 deductible or minimum limits that won’t cover a serious accident.
Coverage options and coverage requirements to compare
California requires at least $30,000 per person and $60,000 per accident for injuries you cause, plus $15,000 for property damage. Those minimums are low compared with what an accident can cost, so when you compare quotes, line them up side by side on:
- Liability limits. Are both quotes at the same limits? A cheaper quote at minimum limits isn’t the same product.
- Collision and comprehensive. These pay for your own car. A lender or leasing company will require both.
- Deductibles. How much would you pay out of pocket before the policy pays?
- Uninsured motorist coverage. This protects you if the other driver has no insurance.
- Extras. Rental reimbursement and roadside assistance usually cost little and are useful if you depend on the car for work.
- Payment terms. What’s due today, what’s due each month, and what happens if a payment is late.
International car insurance and overseas insurance
A lot of drivers ask whether the car insurance they already have at home, or an “international car insurance” plan they found online, will cover them here. For a short trip, a travel or rental product may be fine. For a car you buy, register, and drive every day in California, it usually isn’t. California needs an insurance policy that meets state liability limits and that the DMV, your lender, and the other driver’s insurance company will recognize after an accident.
Overseas insurance is still useful in a different way. Even if it can’t cover your car here, a letter from that insurance company showing years of claim-free coverage is one of the best documents you can bring to us. It’s proof the underwriter can use, and with most of the carriers we work with it helps your price.
Discounts worth asking about
Discounts vary from one insurance company to the next, so ask which ones you qualify for before you buy. Common ones include paying the term in full, insuring more than one car, and combining car insurance with renters insurance. Some discounts depend on a driving record the insurer can verify, which is one more reason to bring your home-country records on the first call. A discount should never be the reason you pick lower limits, though. The insurance coverage itself matters more than a few dollars off.
Which situation are you in?
The best policy also depends on why you’re driving in California and for how long.
| Your situation | What usually fits |
|---|---|
| New resident who just bought or is buying a car | Your own California policy, bound before you drive the car home. If you’re staying, you’ll also need a California license. |
| Working in California on a temporary assignment | Your own policy on the car you buy or lease. Tell us how long you expect to stay so we can set it up the right way. |
| International student | Your own policy with your foreign license. Our post on auto insurance for international students covers roommates, school breaks, and graduation. |
| Visitor driving a relative’s car | Usually the car owner’s policy matters most. If you’ll drive it regularly, the owner should add you to their policy. Our post on how to add an international driver to car insurance explains how that works. |
| Visitor renting a car | Rental coverage through the rental company, or coverage you may already have through a credit card. A long-term personal policy usually isn’t needed. |
How to get an insurance quote that holds up
The car insurance quote you get should be the price you pay. Quotes change at the last minute when information was missing or wrong at the start, so give us the full picture on the first call:
- A clear copy of both sides of your license
- The address where the car will be garaged
- The VIN, which is on the purchase paperwork or the driver-side dashboard
- Names and license details for every driver in your household
- Your driving record and no-claims letter from home
After you approve it and pay the deposit, your insurance coverage can usually start that day, and we’ll send proof of insurance to you, your dealer, or your lender.
Why foreign drivers work with IIS Insurance Services
IIS Insurance Services is licensed in California and works with several insurance companies that write foreign and international licenses. So we can line up insurance options side by side instead of sending you to whichever company answers first. We look for a carrier that won’t surcharge you just for the license, we ask for your home-country history so it can be credited, and we set you up with monthly payments. And if English isn’t your first language, we can help you in seven languages.
Frequently asked questions
Which company is best for foreign drivers in California?
There isn’t one insurance company that’s best for everyone. The best one for you is the one that accepts your license without a big surcharge, credits your driving history, and fits your car and budget. That changes from driver to driver, which is why comparing several insurance companies helps.
Will I pay more because my license is from another country?
Not necessarily. With the carriers we work with, your price comes from the same underwriting factors as any driver. What can raise the price is having no proof of your driving history, so it’s a good idea to have it handy.
Can I use my insurance from back home?
Usually not for a car you live with and drive in California. Check the policy’s territory and limits, and talk to us before you rely on it.
Can someone with a U.S. license insure my car for me?
Only if they’re really the main driver. If you drive the car, you need to be listed. Listing someone else to lower the price can lead to a denied claim.
How fast can I get covered?
Usually the same day, as soon as your documents, the car’s details, and the down payment are in.
Is a California license required to get insured?
You don’t need one to get insured. If you become a resident and get a California license, tell us so we can update your policy. In most cases this will reduce your rate.
Get the best car insurance for foreign drivers
If you drive in California with a foreign or international license, call IIS Insurance Services at (877) 210-9514. We’ll compare carriers that accept your license, look for credit for your driving history, and set you up with monthly payments and same-day coverage.
For the official requirements, see the California Department of Insurance and the California DMV.
Reviewed by George Karapetyan, IIS Insurance Services. CA license #0E94849, agency license #0G56765. Last reviewed October 2026.